
 Search


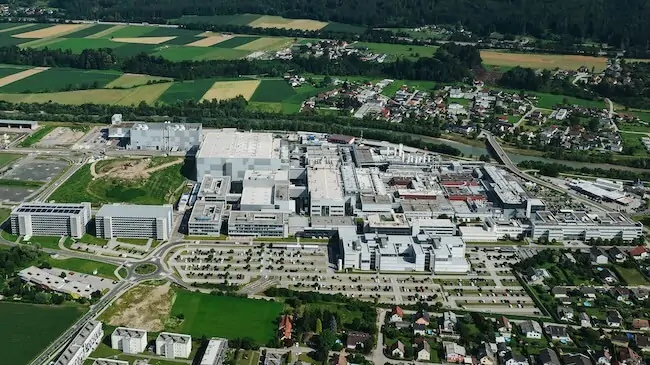
Infineon Technologies expects revenue from power semiconductors for AI and conventional data centers to approach €4 billion in fiscal 2027, versus approximately €2.2 billion in fiscal 2026. The FY2026 total comprises €1.7 billion from AI data centers and €500 million from traditional data centers, according to its November 10 investor presentation. That business nearly doubled from FY2025, as higher accelerator power demands increased spending on conversion, regulation and distribution devices.
The German semiconductor manufacturer reported FY2026 group revenue of €16.353 billion, up 12%, and Segment Result of €3.223 billion, equivalent to a 19.7% Segment Result Margin. Fiscal fourth-quarter revenue was €4.706 billion, with a 23.8% Segment Result Margin. Infineon projects FY2027 group revenue of approximately €20 billion and a Segment Result Margin in the mid-20% range. Planned investments total €3.0–3.5 billion, while adjusted free cash flow is forecast at approximately €2.2 billion. FY2027 ends September 30, 2027.
The AI power opportunity extends from facility-level AC/DC conversion and emerging 800V DC distribution to intermediate bus converters, point-of-load regulation and vertical power delivery near accelerators. Infineon supplies silicon, silicon carbide and gallium nitride devices and added digital power-management expertise through its October 2026 acquisition of C2i Semiconductors. Management estimates Infineon semiconductor content at roughly $175 per kilowatt of AI system power today, within a $100–250/kW range depending on architecture. This is a company estimate of semiconductor content, not data center revenue per kilowatt of installed capacity.
“Infineon closed the fiscal year 2026 with another record quarter and enters the new fiscal year with continued strong momentum,” said Jochen Hanebeck, CEO of Infineon, in the November 10 earnings announcement.
| Infineon FY2026 Results and FY2027 Outlook | |
| FY2026 revenue | €16.353 billion · 12% year-on-year growth |
| FY2026 Q4 | €4.706 billion revenue · 23.8% Segment Result Margin |
| FY2026 earnings | €3.223 billion Segment Result · 19.7% Segment Result Margin · €1.73 adjusted EPS |
| FY2026 cash flow | €993 million free cash flow · €1.925 billion adjusted free cash flow |
| FY2026 data center power | ~€2.2 billion · €1.7B AI + €0.5B traditional |
| FY2027 data center outlook | Close to €4 billion · management forecast, including traditional data centers |
| FY2027 group outlook | ~€20 billion revenue · Segment Result Margin mid-20% |
| FY2027 cash flow / investment | ~€2.2B adjusted free cash flow · €3.0–3.5B planned investments |
| Power semiconductor content | ~$175/kW estimated current average; $100–250/kW architecture-dependent range |
Analysis
Infineon’s data center outlook illustrates how increasing AI accelerator density is expanding the semiconductor content of power delivery. Moving electrical energy through a high-density rack requires high-voltage conversion, intermediate distribution and lower-voltage multiphase regulation close to the processor. For a given power level, higher distribution voltage reduces current and associated conductor losses, but introduces additional demands for insulation, fault protection and safe service operations.
The company participates in several segments of this conversion chain. Silicon carbide supports high-voltage stages, including solid-state transformers; gallium nitride devices enable high-frequency conversion at other stages; and silicon power devices and digital controllers address regulation and system operation. Its 2026 C2i acquisition added expertise in software-defined power management and vertical delivery. Infineon’s planned Villach 300mm GaN manufacturing expansion and its 300mm SiC feasibility milestone address different parts of longer-term semiconductor supply, although the SiC demonstration is not yet qualified volume production.
Infineon’s analyst-call material points to continued supply constraints in the AI power business and associated manufacturing expansion. Its FY2027 outlook is management guidance rather than booked sales. Multiyear customer reservation agreements that include negotiations should likewise not be equated to firm backlog. The relevant operational milestones are manufacturing qualification, product availability, design wins and the conversion of customer reservations into recognized revenue.
| Company Profile | Infineon Technologies AG | |
| Headquarters | Neubiberg, Germany |
| CEO | Jochen Hanebeck |
| Status | Public company · FSE: IFX / OTCQX: IFNNY |
| Website | https://www.infineon.com/ |
| Technology | CoolSiC silicon carbide · CoolGaN gallium nitride · silicon power devices · digital power management |
| AI infrastructure focus | Grid-to-core power conversion · 800V DC · intermediate bus conversion · multiphase and vertical power delivery |
| FY2026 revenue | €16.353 billion |
| FY2027 forecast | ~€20 billion group revenue · data center power close to €4 billion |
| Markets | AI data centers · automotive · energy infrastructure · industrial power · IoT |
We’re tracking developments in power semiconductors and AI infrastructure. Follow ongoing coverage at Converge Digest Semiconductors and Data Centers.

-
 C114 Communication Network
-
 Communication Home
