
 Search


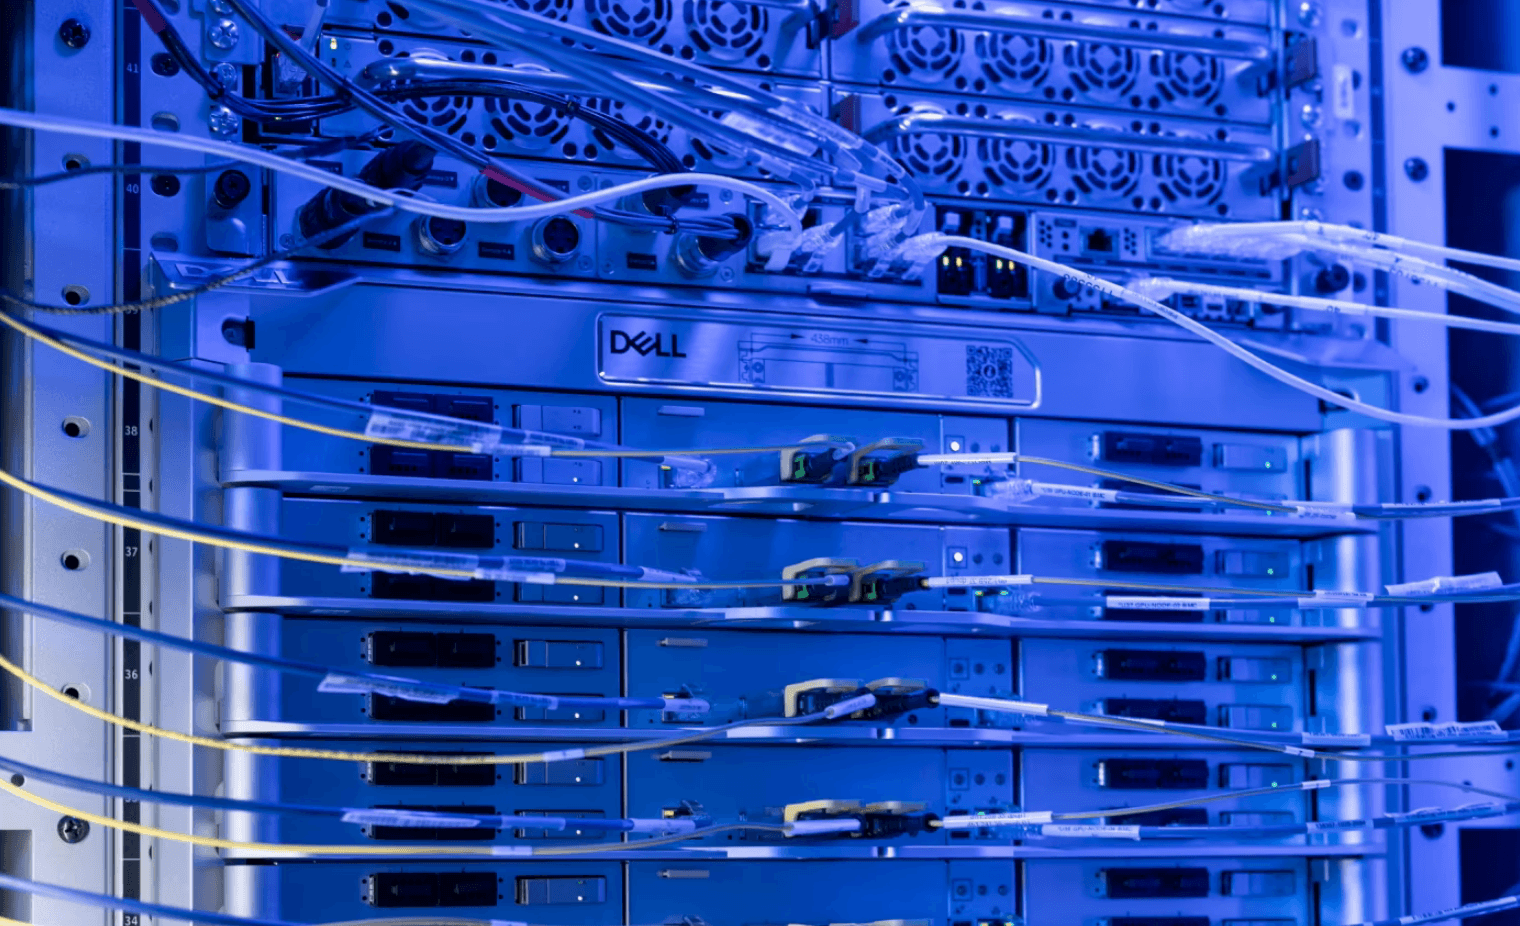
CoreWeave reported third-quarter 2026 revenue of $3.661 billion, up 168% year over year, as the specialized AI cloud operator expanded GPU deployments and grew its revenue backlog to $132.5 billion. The company raised full-year revenue guidance to $13.0 billion–$13.3 billion and projected an annualized exit revenue run rate of $20 billion–$21 billion. GAAP operating income reached $207 million, but net interest expense of $846 million contributed to a $709 million GAAP net loss. The combination illustrates how rapidly expanding AI cloud capacity is generating revenue while requiring substantial external financing.
Financing was a central subject of CoreWeave’s November 10 earnings call. The company expects approximately $9 billion in customer prepayments and deposits over the following three months, including amounts associated with recontracting previously deployed infrastructure. CoreWeave raised approximately $4.2 billion through convertible notes in the quarter and established additional lending and equity-financing capacity. Its funding model combines operating cash flow, customer-specific secured loans, prepayments and other capital-market instruments, with financing needs tied to construction, GPU procurement and deployment schedules.
CoreWeave ended September with more than 1.7 GW of active power across 52 data centers and more than 4.6 GW of contracted power. The company reported approximately $14.5 billion in third-quarter capital expenditures under a measure that includes certain leased equipment, and increased its full-year capital expenditure guidance to $37 billion–$39 billion. It highlighted production deployments of NVIDIA Vera Rubin NVL72 for Cognition and a workload-specific 4.8-fold inference token-throughput improvement over GB200 NVL72. The company is also broadening its Forge platform across training, inference, evaluation and agent development, seeking to generate software and service revenue alongside GPU rentals.
“Our growth is supported by multiple sources of funding, including financing backed by customer contracts, operating cash flow,” said Michael Intrator, CoreWeave co-founder, chairman and CEO, in the company’s November 10 earnings release.
| CoreWeave Q3 2026 — Key Developments |
| • Revenue reached $3.661 billion, up 168% year over year; revenue backlog was $132.5 billion. |
| • GAAP operating income was $207 million, but a $846 million net interest expense contributed to a $709 million GAAP net loss. |
| • Quarterly capital expenditures were $14.511 billion under the company’s definition, including qualifying finance-lease assets. |
| • Customer prepayments and deposits expected over the next three months total approximately $9 billion, according to management. |
| • CoreWeave reported over 1.7 GW of active power across 52 data centers and over 4.6 GW of contracted power. |
| • FY2026 guidance calls for $13.0–$13.3 billion revenue and $37–$39 billion capital expenditures. |
| • NVIDIA Vera Rubin NVL72 has entered production for Cognition; a reported 4.8× token-throughput comparison is workload-specific. |
Investor-Call Analysis: Funding, NVIDIA and AI Cloud Trends
Management reported $46.9 billion in total debt at September 30, while weighted-average borrowing costs had declined to approximately 7.9%. The quarterly net interest expense of $846 million was substantially greater than GAAP operating income. CoreWeave expects roughly $9 billion of customer prepayments and deposits over three months, which would provide an additional source of funding but is prospective. Convertible issuance, secured term loans and a new at-the-market equity program increase financing alternatives while introducing different leverage and dilution considerations.
| Investor Call — Financing and GPU Economics | |
| Debt and funding | Total reported debt $46.9B at September 30; weighted-average debt cost approximately 7.9%, according to management. |
| Incoming prepayments | Approximately $9B of customer prepayments/deposits expected within three months; timing is prospective. |
| New financing | Approximately $4.2B in convertible notes during the quarter; $2.6B delayed-draw term loan facility. |
| Hardware renewal | Management says Ampere/Hopper pricing increased 30%–50% quarter over quarter, reflecting company-observed contract pricing. |
| Recontracting | ~130,000 GPUs come off existing contracts in 2027 and ~170,000 in 2028, according to management. |
| Renewal projections | Nearly $4B potential incremental annualized revenue for 2027 renewal cohort and nearly $10B including 2028; not secured backlog. |
| Demand claim | Management describes qualified demand through 2027 as approximately 10× available capacity; not independently measured. |
CoreWeave reported that Ampere and Hopper GPU pricing had increased 30%–50% sequentially and estimated that about 130,000 GPUs would roll off existing contracts in 2027, followed by roughly 170,000 in 2028. Management’s potential incremental revenue estimates reflect its expectations for recontracting these units; they are distinct from signed backlog. Such reuse can reduce the need to retire older equipment at the end of the initial lease, but sustained demand and operating costs remain decisive.
NVIDIA is referenced both as a strategic technology supplier and through customer deployments of GPU rack systems. CoreWeave’s Cognition Vera Rubin NVL72 implementation demonstrates the importance of Scale Up connections within a rack and Scale Out networks across AI clusters. As inference and agentic workloads expand, CPU execution, memory access, network latency and orchestration become part of the economics of GPU utilization.
On demand, management described qualified opportunities through 2027 as approximately ten times currently available capacity. That claim reflects CoreWeave’s sales pipeline assessment, not an independent market estimate. Customers are increasingly seeking combinations of long-term dedicated infrastructure and flexible short-term access for inference and model development. The company’s Forge software strategy aims to connect training, post-training, evaluation and inference workflows.
Analysis
CoreWeave’s revenue backlog covers estimated future revenue under committed contracts, subject to capacity delivery and service requirements; it is not cash already received. Likewise, contracted megawatts are not the same as energized GPU capacity. The gap between more than 4.6 GW contracted and 1.7 GW active indicates the construction, electrical interconnection, cooling and commissioning work required before some of those contracts can generate revenue.
The financing strategy is increasingly tied to contracted infrastructure. Management described delayed-draw facilities backed by customer relationships, alongside customer prepayments and operating cash flow. The company nonetheless bears material interest expense and faces execution risks from equipment delivery, power availability, customer concentration, refinancing and capital-market conditions. Its target for adjusted net profitability in the first half of 2028 is a forecast, not a realized outcome.
NVIDIA remains central to CoreWeave’s hardware roadmap. Vera Rubin NVL72 is a rack-scale system integrating accelerator, CPU, memory and high-speed interconnect resources; deployment requires coordinated power, liquid cooling, network fabric and software operations. The performance claim for Cognition should be read as a result for the stated workload rather than a general benchmark for all inference applications.
Management also sees a possible second monetization cycle for installed GPUs. Its estimate of nearly $4 billion of incremental annualized revenue from 2027 renewals, and nearly $10 billion including the 2028 renewal opportunity, depends on utilization and prevailing prices when equipment leaves its first contract. These estimates are not booked revenue or guaranteed transactions. If realized, reuse could extend economic returns beyond the original contract period and make asset lifecycle management an increasingly important competitive factor for AI cloud operators.
| Company Profile — CoreWeave | |
| Headquarters | Livingston, New Jersey, United States |
| Founded | 2017 |
| Leadership | Michael Intrator, co-founder, chairman and CEO |
| Listing | Nasdaq: CRWV |
| Core business | Purpose-built GPU cloud infrastructure for AI training, inference and related services |
| Technology | NVIDIA accelerated computing, rack-scale fabrics, high-speed Ethernet, liquid cooling, CoreWeave Forge |
| Footprint | Over 1.7 GW active and 4.6 GW contracted power at September 30, 2026 |
| Website | coreweave.com |

-
 C114 Communication Network
-
 Communication Home
